Market Analysis – January 2020

James DeVuyst • January 3, 2020

Market Outlook

I wanted to take this time to provide an update on the year that was and the decade that is to come. 2019 overall was a slow year, not only growth, but sales activity. We saw below average home sales activity and moderate price declines throughout 2019 as most of us have seen on our recent property tax assessments. The GVRD saw a -18.2% drop in property values across all types of homes, while Squamish, Whistler, and Pemberton saw no change or an increase in values.

Heading into 2020 MLS is predicting a rise in sales of 3.6% over 2019, which was overall a slow year. Through the economic slowdowns currently happening in China, and other areas of the world this could potentially continue throughout 2020, where may see a further decrease in sales activity and value.

As we look at the mortgage industry as a whole, we have gone through some major disruptions over the past two years. The implementing of the mortgage stress test was a major factor in declining sales activity as well as a sore spot for many first-time buyers. This coming year however, the Finance Minister of Canada has said they will look to make the mortgage stress test “more fluid”. We may start to see changes in the qualification rates, i.e. going back to contract rate qualification (approximately 2% lower). We could also see the introduction of a 30-year amortization for high ratio insured mortgages (up from the current 25 years). This would open the gates and allow homebuyers to qualify for a higher purchase price, which we all know Vancouver has.

We are seeing rents increasing at an alarming rate, while prices of homes have fallen, this looks good for investors looking to increase their property portfolio.


Financial Focus

My suggestion, as we start a new decade, is to revisit your financial situation. BC has lost over $90 billion in home values over the past year. This is quite alarming as Canadians largest financial asset loses value, and Canadians debt level remains at all time highs.

If you have a mortgage coming up in 2020 or 2021 or you have a variable rate sitting above the discount of prime -0.30% to -0.50%, give us a call for a market update today.

I would also recommend that if you have any outstanding consumer debt, we look at all options to reduce this burden going into 2020 as we don’t know what the world economy has in store in an ever increasingly unstable global outlook.

For investors looking to refinance their home and purchase a second property, there is no better time than now as values of homes are decreasing.  If you’re needing to refinance your own home, it would be prudent to look at these options.

Please contact me directly at 604-512-5552 or email me at  james@devuyst.ca  for your personalized homeowner analysis today!

James De Vuyst, BComm

RECENT POSTS
By James De Vuyst September 17, 2026
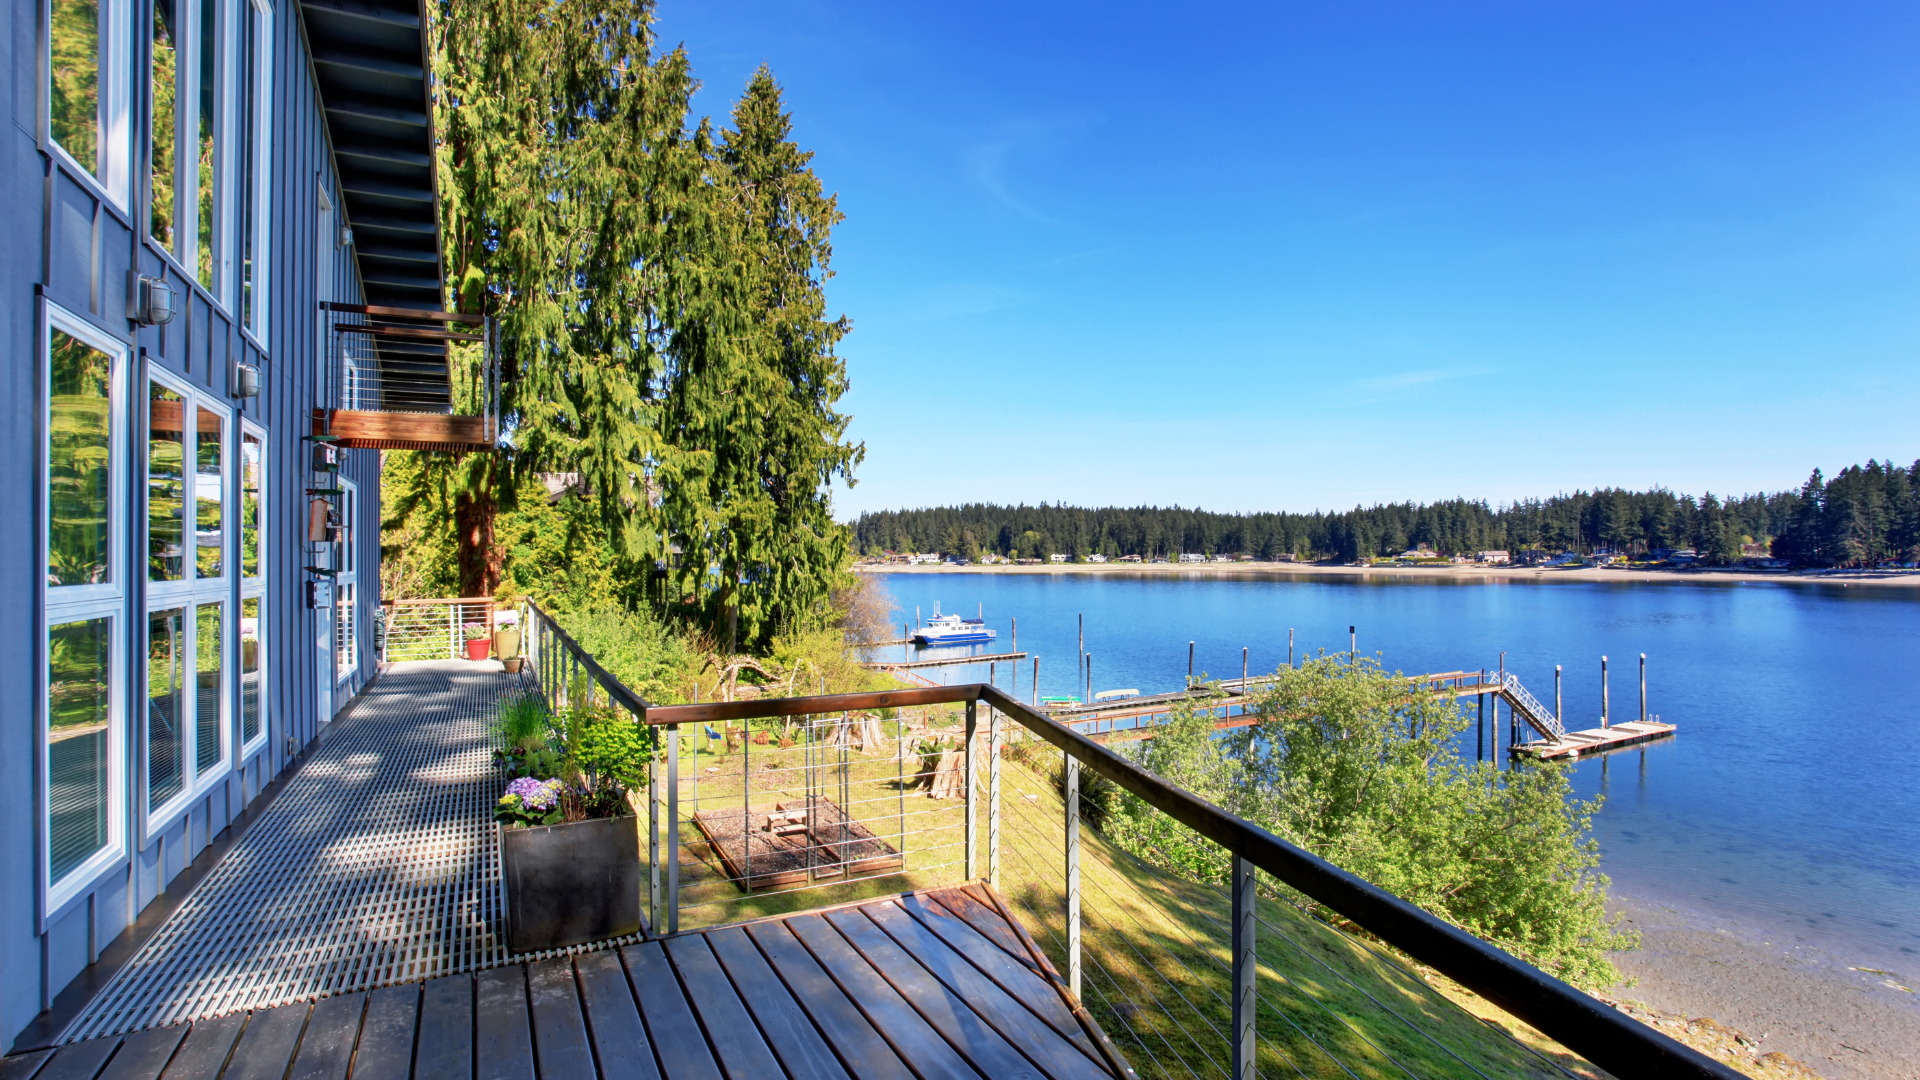
Owning a vacation home or an investment rental property is a dream for many Canadians. Whether it’s a cottage on the lake for family getaways or a rental unit to generate extra income, real estate can be both a lifestyle choice and a smart financial move. But before you dive in, it’s important to know what lenders look for when financing these types of properties. 1. Down Payment Requirements The biggest difference between buying a primary residence and a vacation or rental property is the down payment. Vacation property (owner-occupied, seasonal, or secondary home): Typically requires at least 5–10% down, depending on the lender and whether the property is winterized and accessible year-round. Rental property: Usually requires a minimum of 20% down. This is because rental income can fluctuate, and lenders want extra security before approving financing. 2. Property Type & Location Not all properties qualify for traditional mortgage financing. Lenders consider: Accessibility : Is the property accessible year-round (roads maintained, utilities available)? Condition : Seasonal or non-winterized cottages may not meet standard lending criteria. Zoning & Use : If it’s a rental, lenders want to ensure it complies with municipal bylaws and zoning regulations. Properties that fall outside these norms may require financing through alternative lenders, often with higher rates but more flexibility. 3. Rental Income Considerations If you’re buying a property with the intent to rent it out, lenders may factor the rental income into your mortgage application. Long-term rentals : Lenders typically accept 50–80% of the expected rental income when calculating your debt-service ratios. Short-term rentals (Airbnb, VRBO, etc.) : Many traditional lenders are cautious about using projected income from short-term rentals. Alternative lenders may be more flexible, depending on the property’s location and your financial profile. 4. Debt-Service Ratios Lenders use your Gross Debt Service (GDS) and Total Debt Service (TDS) ratios to determine if you can handle the mortgage payments alongside your other obligations. With investment or vacation properties, lenders may apply stricter guidelines, especially if your primary residence already carries a large mortgage. 5. Credit & Financial Stability Your credit score, employment history, and overall financial health still matter. Since vacation and rental properties are considered higher risk, lenders want reassurance that you can handle the additional debt—even if rental income fluctuates or the property sits vacant. 6. Insurance Requirements Rental properties often require specialized landlord insurance, and vacation homes may need coverage tailored to seasonal or secondary use. Lenders will want proof of adequate insurance before releasing mortgage funds. The Bottom Line Buying a vacation property or rental can be exciting, but financing these purchases comes with extra rules and considerations. From higher down payments to stricter property requirements, lenders want to be confident that you can handle the responsibility. If you’re considering a second property, the best step is to work with a mortgage professional who can compare lender requirements, outline your options, and find the financing that works best for you. Thinking about making your dream of a vacation or rental property a reality? Connect with us today.
By James De Vuyst September 3, 2026
Owning a home feels great—carrying a large mortgage, not so much. The good news? With the right strategies, you can shorten your amortization, save thousands in interest, and become mortgage-free sooner than you think. Here are four proven ways to make it happen: 1. Switch to Accelerated Payments One of the simplest ways to reduce your mortgage faster is by moving from monthly payments to accelerated bi-weekly payments . Instead of 12 monthly payments a year, you’ll make 26 half-payments. That works out to the equivalent of one extra monthly payment each year, shaving years off your mortgage—often without you noticing much difference in your budget. 2. Increase Your Regular Payments Most mortgages allow you to boost your regular payment by 10–25%. Some even let you double up payments occasionally. Every extra dollar goes directly toward your principal, which means less interest and faster progress toward paying off your balance. 3. Make Lump-Sum Payments Depending on your lender, you may be able to make lump-sum payments of 10–25% of your original mortgage balance each year. This option is ideal if you receive a bonus, inheritance, or other windfall. Applying a lump sum directly to your principal immediately reduces the interest charged for the rest of your term. 4. Review Your Mortgage Annually It’s easy to put your mortgage on auto-pilot, but a yearly review keeps you in control. By sitting down with an independent mortgage professional, you can check if refinancing, restructuring, or adjusting terms could save you money. A quick annual review helps ensure your mortgage is always working for you—not against you. The Bottom Line Paying off your mortgage early doesn’t require a massive lifestyle change—it’s about making smart, consistent choices. Whether it’s accelerated payments, lump sums, or regular reviews, every step you take helps reduce your debt faster. If you’d like to explore strategies tailored to your situation—or want a free annual mortgage review—let’s connect. I’d be happy to help you find the fastest path to mortgage freedom.
By James De Vuyst September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.